Cooling Housing Market Contrasts with Strong Rents, Boosting Investor Appeal
Australia’s property market is showing two very different trends at the same time. Home values are falling across much of the country, while rents and rental yields remain comparatively strong, creating a more complex environment for buyers, sellers and investors.
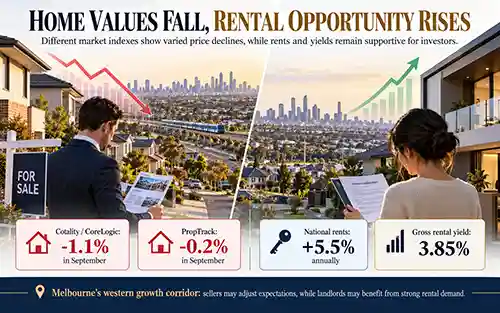
Cotality’s September 2026 Home Value Index recorded a 1.1% national decline in dwelling values for the month, while PropTrack’s separate index reported a milder 0.2% fall. The difference reflects the way each index measures the market, but both point in the same direction: national housing conditions have weakened and prices are continuing to adjust.
At the same time, the rental market remains much stronger. National rents are around 5.5% higher than a year ago, while gross rental yields have increased to 3.85%, their highest level since 2019. Falling property values combined with continued rent growth are helping lift yields even as capital values soften.
This creates an important distinction between capital growth and rental performance. A property may be declining in value in the short term while still producing stronger rental income than it did a year earlier. For investors, that means the current market cannot be assessed purely by looking at sale prices.
For Melbourne’s western growth corridor, this could create opportunities in areas where rental demand remains strong and entry prices are becoming more competitive. Investors may find that softer purchase prices improve gross yields, especially in suburbs supported by population growth, transport, schools, employment access and limited rental supply.
However, higher yields do not automatically mean stronger profitability. Investor mortgage rates remain elevated, and finance costs can absorb a large share of rental income. Property management fees, maintenance, insurance, council rates, owners corporation expenses and vacancy periods also need to be considered before deciding whether an investment is genuinely cash-flow positive.
For existing landlords, the current environment may be more favourable. Those who purchased earlier at lower prices or hold substantial equity may benefit from higher rents without facing the same level of borrowing pressure as new investors.
For new entrants, the equation is tighter. Buying at a lower price can be attractive, but higher interest rates mean repayments remain substantial. Investors therefore need to place greater emphasis on rental yield, tenant demand and long-term fundamentals rather than relying on short-term capital growth.
Sellers in Melbourne’s west may also need to adjust expectations. Softer dwelling values and weaker buyer demand can make pricing more important, especially if buyers have more properties to choose from. Homes that are realistically priced and well presented are likely to attract stronger interest than listings based on previous peak values.
For owner-occupiers, the current market may provide more negotiating power, but affordability remains constrained by higher borrowing costs. Even if prices fall, buyers may not necessarily be able to borrow as much as they could when interest rates were lower.
The contrast between weaker sale prices and stronger rents is a reminder that different parts of the property market can move in different directions at the same time. In Melbourne’s western growth corridor, this may create opportunities for carefully selected rental properties even while broader capital values remain under pressure.
Overall, the market is becoming more selective. Buyers may benefit from softer prices, sellers need realistic expectations, and investors should focus on sustainable rental returns, manageable debt and long-term suburb fundamentals rather than assuming that falling values automatically make every property a good investment.
Summarised by Ravs Realtors from reporting by Australianpropertyupdate.