Investment Property Costs Beyond the Purchase Price in Melbourne's West
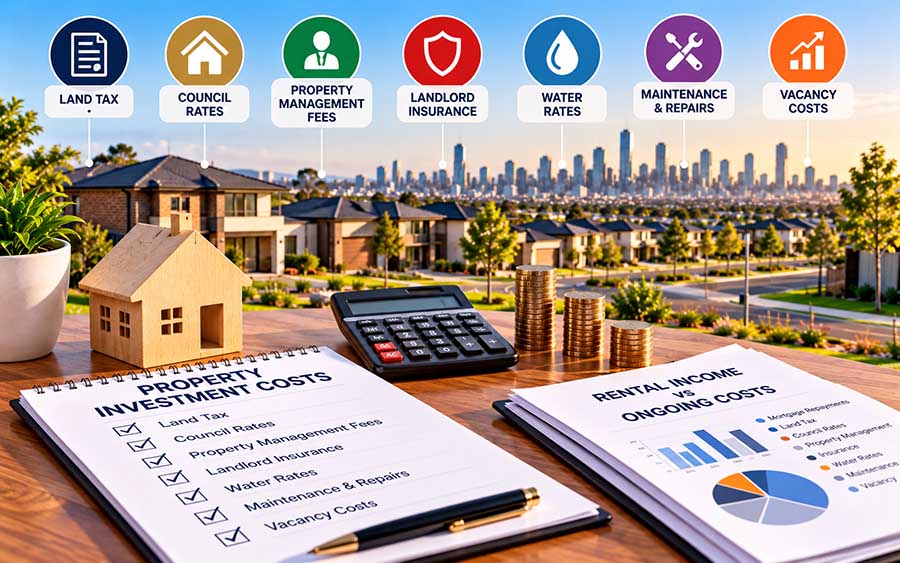
Investing in property across Melbourne’s western suburbs can offer strong long-term potential, but profitability depends on much more than the mortgage repayment. Land tax, council rates, management fees, insurance, water charges, maintenance and vacancy costs can all significantly affect the true return from an investment.
One of the most important ongoing costs is Victorian land tax. It is calculated on the total taxable site value of Victorian land you own as at midnight on 31 December of the previous year. Your principal place of residence is generally exempt, but residential investment properties are commonly taxable. For individuals, land tax applies from a total taxable land value of $50,000, while trusts generally have a lower $25,000 threshold and different rates.
Absentee owners can also face an additional surcharge, which can materially increase the annual cost of holding Victorian property. Investors purchasing through companies or trusts should therefore understand the ownership structure before calculating expected returns.
Council rates are another unavoidable expense. Most Victorian councils calculate rates using a property’s Capital Improved Value, although valuations can also include Site Value and Net Annual Value. While the Victorian rate cap limits growth in a council’s total rate revenue, it does not cap the increase on an individual property, so a particular owner’s bill can rise by more than the headline rate cap if the property’s valuation changes relative to others in the municipality.
Investors should also be aware of Vacant Residential Land Tax. The tax now applies statewide to qualifying residential properties that are vacant for more than six months in the previous calendar year. The standard rate begins at 1% of the property’s Capital Improved Value and can rise to 2% and then 3% for consecutive years of liability.
From 2026, the rules also capture certain undeveloped residential land in metropolitan Melbourne that has remained undeveloped for at least five continuous years and is capable of residential development. This is particularly relevant in growth areas where investors may be holding land for future construction.
Property management is another significant operating cost. Fees vary between agencies and can include ongoing management, tenant placement, advertising, lease renewals and other services. Investors should request a complete fee schedule rather than looking only at the headline management percentage.
Landlord insurance is also worth budgeting for. A policy may provide protection against risks such as tenant-related damage, loss of rent and liability, depending on the cover selected. Premiums vary according to the property, insurer, excess and level of protection.
Water costs can also be divided between owner and tenant responsibilities. Owners generally remain responsible for service and infrastructure charges, while tenants may pay usage charges where the property meets the relevant requirements.
Maintenance is another expense that can easily be underestimated. Appliances fail, heating and cooling systems need servicing, plumbing issues occur and properties require ongoing upkeep. Setting aside a maintenance reserve can help prevent unexpected repairs from disrupting cash flow.
Vacancy should also be included in any investment budget. Even in areas with strong rental demand, there may be periods between tenants when no rent is received while mortgage payments and other expenses continue.
For investors in Melbourne’s western growth corridor, these costs should be considered alongside expected rental income before purchasing. A property with an attractive headline rental yield may produce a very different net return once land tax, rates, management, insurance, maintenance and finance costs are deducted.
The western corridor continues to offer opportunities supported by population growth, infrastructure development and relatively affordable entry prices, but successful investing still requires disciplined cash-flow planning.
Before committing to a purchase, investors should obtain professional advice on taxation and ownership structure, review local council charges and request a detailed property-management fee schedule.
Understanding the full cost of ownership from the beginning makes it easier to compare opportunities realistically and build an investment strategy that remains sustainable over the long term.