Older Australians Hope for Property Price Falls to Aid Younger Generations
Australia’s housing affordability debate is increasingly becoming an intergenerational issue, with many younger Australians finding it difficult to enter the property market after years of strong price growth. At the same time, there is growing public discussion about whether a period of softer property prices could help restore a better balance between existing homeowners and people trying to buy their first home.
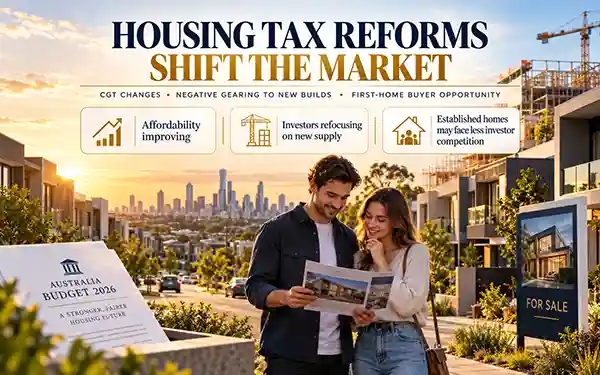
The Federal Government’s 2026–27 Budget introduced major housing and tax reforms aimed at improving access to home ownership and changing the way residential property investment is treated. These reforms include limiting negative gearing for future residential property investment to new builds from the 2027–28 income year, while existing investments purchased before the announced cut-off remain protected under the current arrangements.
The Government is also replacing the existing 50% capital gains tax discount with an inflation-adjusted system from July 2027, together with a minimum tax rate on real capital gains. New-build properties will retain more favourable treatment, reflecting the Government’s intention to direct more investor capital toward increasing housing supply rather than competing for established homes.
For first-home buyers, these changes could gradually alter the competitive environment. If fewer investors target established properties, some buyers may face less competition when purchasing an existing home. The Government has stated that its broader housing reforms are designed to improve the position of first-home buyers while encouraging more investment into new housing construction.
This could be particularly relevant across Melbourne’s western growth corridor, where affordability remains one of the area’s strongest attractions. Suburbs with newer housing, house-and-land opportunities and relatively lower entry prices may become increasingly attractive to first-home buyers who are priced out of more expensive parts of Melbourne.
At the same time, the reforms could influence investor behaviour. Investors considering established homes after the new rules take effect may have less incentive to purchase properties that generate short-term tax losses, while newly built homes could become comparatively more attractive because of the concessions retained for that sector.
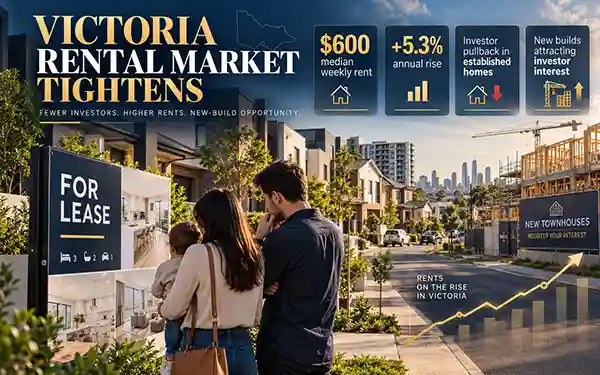
That shift could have mixed implications for the rental market. If fewer investors purchase established properties, rental supply in some areas could be affected. On the other hand, stronger incentives to invest in new housing may help increase the overall supply of dwellings over time, which is one of the Government’s stated policy objectives.
For Melbourne’s western growth corridor, the changes may therefore create a different mix of demand rather than simply reducing investment altogether. First-home buyers may benefit from reduced competition in parts of the established market, while investors may increasingly focus on new builds, growth-area developments and properties offering stronger rental fundamentals.
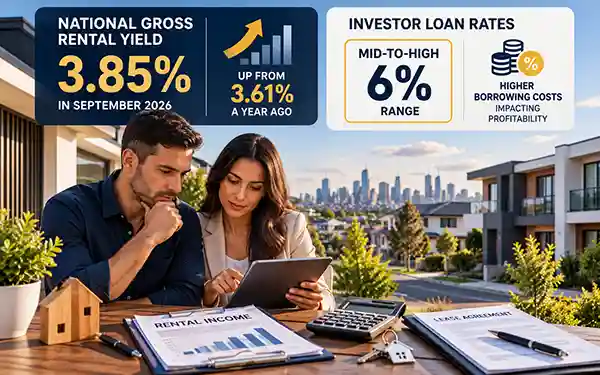
Property owners and investors should also be careful not to assume that policy reform alone will determine market direction. Interest rates, borrowing capacity, employment, population growth, new housing supply and local infrastructure will continue to play a major role in property values and rental demand.
The broader shift reflects an attempt to make housing more accessible to younger Australians while still encouraging investment in new supply. For buyers, sellers and investors in Melbourne’s west, understanding how these reforms change incentives could become just as important as following movements in property prices themselves.
Summarised by Ravs Realtors from reporting by The Guardian.