RBA Hikes Reduce Household Borrowing Power
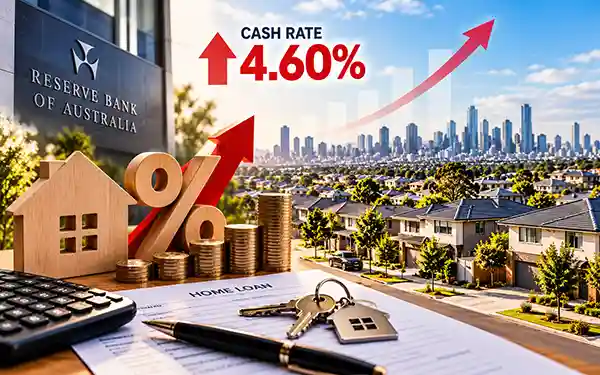
The Reserve Bank of Australia’s September decision to lift the cash rate to 4.60% has flowed through quickly to home loan rates, increasing borrowing costs for households and further reducing the amount many buyers can afford to borrow.
The RBA raised the cash rate by 25 basis points on 29 September 2026, taking it to 4.60%. Major lenders subsequently increased variable mortgage rates, with several of the big banks lifting advertised variable rates by the same 0.25 percentage points in early October.
This increase comes on top of several earlier rate rises in 2026. The RBA has noted that mortgage rates have generally moved broadly in line with changes in the cash rate, meaning higher policy rates are being transmitted directly into household borrowing costs.
For prospective buyers, one of the biggest impacts is reduced borrowing capacity. Lenders assess applicants using serviceability buffers above the actual loan rate, so when mortgage rates rise, the maximum loan amount a household can qualify for can fall even if its income has not changed.
This is particularly important in Melbourne’s western growth corridor, where many first-home buyers and young families rely on larger mortgages to enter the market. Buyers who previously planned to purchase a detached house may now need to reconsider the size, location or type of property they can afford.
Some households may shift toward townhouses, units or smaller homes, while others may look further into more affordable parts of the western corridor. This could support demand in lower-priced segments even while higher-value properties experience greater pressure.
The situation also highlights an important point about housing affordability. Falling property prices do not automatically make homes easier to buy. If interest rates rise at the same time, lower borrowing capacity can offset part or even all of the benefit created by a cheaper purchase price.
For sellers, this means understanding the financial limits of the local buyer pool is becoming increasingly important. Properties priced according to earlier market conditions may take longer to sell if buyers can no longer obtain the finance needed to meet those expectations.
Investors are also affected. Higher variable rates increase holding costs and can reduce cash flow, particularly where properties are highly leveraged. Investors may therefore place greater emphasis on rental yield, purchase price and debt levels before committing to a new property.
At the same time, strong rental demand in parts of Melbourne’s west may help offset some of the pressure from higher interest expenses. However, rental income alone does not eliminate the impact of more expensive finance, especially once insurance, maintenance, land tax and property management costs are considered.
Existing borrowers may also feel the effect as higher rates are passed through to repayments. The RBA has noted that scheduled mortgage payments have risen relative to household disposable income, although most borrowers remain financially resilient and mortgage arrears are still relatively low.
For first-home buyers, the current environment reinforces the importance of obtaining an updated borrowing assessment before searching for property. A pre-approval obtained before the latest rate increase may no longer accurately reflect current lending conditions.
Buyers should also leave room in their budgets for future changes rather than borrowing to the absolute maximum available. This can provide greater flexibility if interest rates remain elevated or living costs continue to rise.
Overall, the September rate increase has made borrowing more expensive at the same time as property prices have softened. For Melbourne’s western growth corridor, this is likely to encourage buyers to become more price-conscious and selective, while increasing demand for more affordable property types and locations.
The opportunities have not disappeared, but affordability is now being shaped as much by the cost of finance as by the price of the property itself. Buyers, sellers and investors who understand that shift will be better positioned to navigate the current market.
Summarised by Ravs Realtors from reporting by Aussie.