RBA Rate Hike Threatens Homebuyer Affordability in Over 100 Suburbs
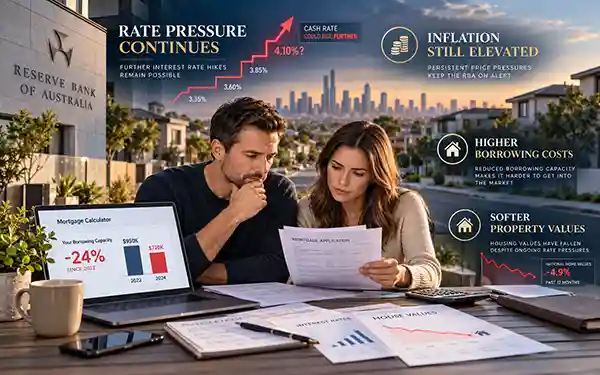
The Reserve Bank of Australia’s latest interest rate increase is putting renewed pressure on homebuyers, with the higher cash rate reducing the amount many households can borrow and forcing buyers to reassess their property budgets.
The RBA lifted the cash rate to 4.60% on 30 September, marking the fourth rate increase of 2026 and taking rates to their highest level since 2011. The cumulative effect of these increases is now being felt across the housing market, particularly among buyers who rely heavily on mortgage finance.
Before the latest decision, analysis estimated that a typical Australian homebuying household could lose close to $20,000 in borrowing capacity from a single 0.25 percentage point increase. The same analysis suggested that the maximum affordable purchase price for an average household could fall from around $877,000 to approximately $858,000, potentially removing more than 100 suburbs and towns from their affordable search range.
For Victorian buyers, the impact was estimated at around $17,000 in reduced borrowing power for a household taking out the state’s average loan. That reduction could move some Melbourne suburbs beyond the financial reach of buyers who were previously able to compete at their median price levels.
This changing borrowing environment is particularly relevant for Melbourne’s western growth corridor, where affordability has traditionally been one of the region’s strongest advantages. Buyers who have seen their approved loan amount reduced may now shift their attention toward more affordable suburbs, smaller homes, townhouses or units.
That could create stronger competition within lower price brackets. While the overall property market may be softer, homes that sit within the borrowing range of first-home buyers and average-income households could attract relatively stronger demand than more expensive properties.
For prospective buyers, this makes budget planning increasingly important. Rather than focusing solely on the maximum amount a lender is willing to provide, buyers should consider monthly repayments, living costs and the financial buffer they will retain after settlement.
Higher rates may also change buyer expectations around property size and location. A household that previously planned to purchase a larger detached home may instead consider a smaller dwelling or move further from the city in order to remain within its borrowing limit.
For sellers in Melbourne’s west, the reduction in buyer borrowing capacity may require a more realistic pricing strategy. A property priced above the financial reach of its likely buyer group could experience longer selling times or fewer offers, even if the home itself remains attractive.
At the same time, more affordable properties may continue to attract competition because they remain accessible to a broader pool of purchasers. Sellers in these lower price ranges should therefore consider both overall market weakness and the strength of demand within their specific segment.
Investors also need to account for the higher cost of finance. Reduced borrowing capacity can limit the price investors are willing or able to pay, while higher mortgage repayments may place greater importance on rental yield, holding costs and cash flow.
The latest rate increase reinforces how quickly financing conditions can change the property market. For buyers in Melbourne’s western growth corridor, the focus is increasingly shifting toward affordability, careful budgeting and properties that remain comfortably within lending limits.
For sellers, understanding the financial capacity of the likely buyer market may now be just as important as understanding comparable sales. As borrowing power falls, realistic pricing and strong presentation could become increasingly important in achieving a successful result.
Summarised by Ravs Realtors from reporting by realestate.com.au.