Selling Your Home: Understanding the Costs in Victoria
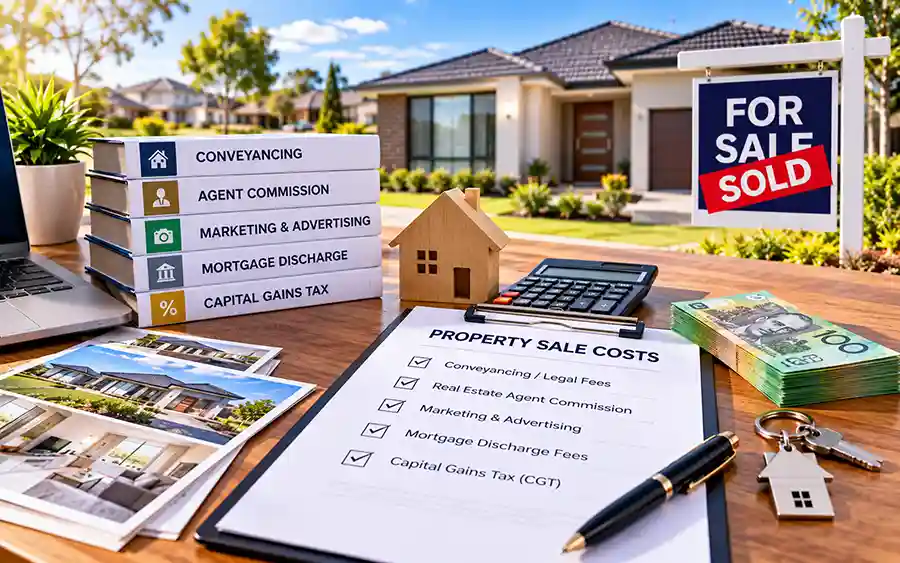
Selling a home in Melbourne’s western suburbs involves more than simply agreeing on a sale price. Legal work, agent fees, marketing, loan discharge costs and possible tax obligations can all affect how much you ultimately receive after settlement.
One of the first expenses is conveyancing or legal work. In Victoria, sellers must provide buyers with a Section 32 Vendor Statement before the buyer signs the contract. This document outlines important information about the property, including title details, mortgages, easements, zoning and outgoings, and is usually prepared by a licensed conveyancer or solicitor.
Conveyancing costs vary depending on the complexity of the property and the professional you use, so sellers should obtain a clear written quote that includes any certificates, searches and other disbursements.
Real estate agent commission is usually one of the largest selling expenses. Recent industry data places the average Melbourne commission at around 1.76% including GST, while Western Melbourne averages about 1.73%. Actual rates vary by suburb, property value and agency, and commission is negotiable.
Marketing is another important part of the budget. Professional photography, floor plans, online advertising, signboards, brochures, auction promotion and premium portal placement can all influence the final campaign cost. Rather than focusing only on the cheapest package, sellers should consider whether the marketing strategy is strong enough to reach the right buyers and maximise competition.
Consumer Affairs Victoria specifically recommends discussing and negotiating both commission and marketing costs before signing the sales authority.
If there is an existing mortgage over the property, the lender will also need to discharge it at settlement. Banks may charge discharge or administration fees, and there can be additional title-registration costs associated with removing the mortgage.
Tax is another area that should not be overlooked. A home that has been your main residence may generally qualify for the main-residence Capital Gains Tax exemption, but different rules can apply where the property has been rented out, used to produce income or has not always been your principal residence. Sellers with these circumstances should obtain advice from a qualified accountant or tax adviser before completing the sale.
For homeowners in Melbourne’s western growth corridor, understanding these expenses early makes it much easier to calculate the likely net proceeds from a sale. A high selling price does not automatically mean the strongest financial result if excessive costs reduce what remains after settlement.
A good selling strategy therefore starts with a clear budget. Ask for written estimates for conveyancing, commission and marketing, confirm any mortgage discharge costs with your lender, and seek tax advice where necessary.
Ultimately, knowing the full cost of selling allows homeowners to make better decisions about pricing, marketing and their next property move. Careful preparation can reduce surprises and help ensure that the final sale delivers the strongest possible outcome.